VAT for the Self-Employed in Spain: How to File Form 303
VAT is not a cost for the self-employed: you charge it to your clients and pay it over to the Tax Agency after deducting the VAT you paid on your purchases. Once you understand that mechanism, the rates and the form 303 deadlines, you avoid cash-flow shocks and most letters from the Tax Agency.
How VAT works: output minus input
You collect VAT on behalf of the Tax Agency and deduct what you pay: you only pay over the difference.
Every invoice subject to VAT adds the tax to the taxable amount. That is output VAT, and it is not yours: you collect it on behalf of the Tax Agency.
When you buy goods or services for your business you pay VAT to your suppliers. That is input VAT, and you can deduct it if you meet the requirements.
- Add up output VATAll the VAT on the invoices you issued in the period.
- Subtract deductible input VATThe VAT on invoices for business expenses, issued to you with your details.
- Check the resultIf it is positive, you pay it. If it is negative, you carry it forward or claim a refund in the last period of the year.
VAT rates and exempt supplies
Choosing the wrong rate is a mistake that carries over quarter after quarter.
| Rate | Applies to… |
|---|---|
| 21% standard | Most professional services, technology, clothing, hairdressing, electricity and repairs. |
| 10% reduced | Hospitality and catering, passenger transport, most food not taxed at 4%, water and certain home renovation work. |
| 4% super-reduced | Bread, milk, cheese, eggs, fruit, vegetables, pulses, olive oil, books, newspapers and medicines for human use. |
With exempt supplies you do not charge VAT and, as a rule, you cannot recover input VAT either. They include:
- Healthcare.
- Accredited education and certain private tuition.
- Insurance and many financial services.
- Residential rentals.
A worked quarterly example
A consultant in the third quarter of 2026, with round numbers.
- Invoicing: €15,000 at 21%
- €3,150
- Expenses: €4,000 at 21%
- − €840
- Business meals: €500 at 10%
- − €50
- Amount payable
- €2,260
If she had €300 left to carry forward from the previous quarter, she would now pay €1,960.
Form 303 deadlines in 2026
Quarterly for almost everyone, and compulsory even if the result is zero.
| Period | Filing deadline | If paying by direct debit |
|---|---|---|
| Q4 2025 + form 390 | By 30 January 2026 | By 27 January |
| Q1 2026 | By 20 April | By 15 April |
| Q2 2026 | By 20 July | By 15 July |
| Q3 2026 | By 20 October | By 15 October |
| Q4 2026 + form 390 | By 1 February 2027 (30 January is a Saturday) | To be set in the 2027 calendar |
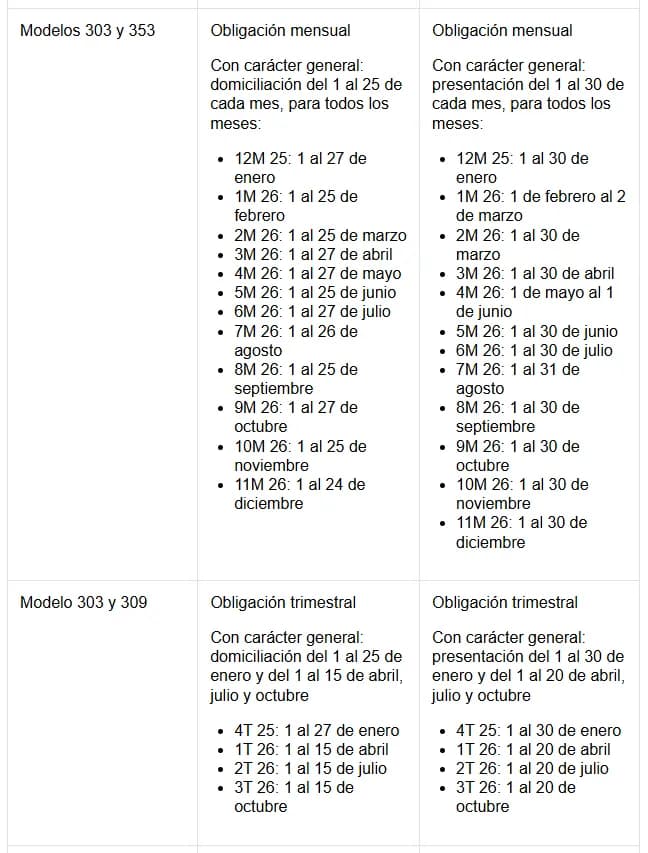
With direct debit, the payment is collected on the last day of the period. Monthly filers (those on the monthly refund register, REDEME, large companies or VAT groups) file form 303 by the 30th of the following month: September by 30 October, October by 30 November and November by 30 December.
- No activity in the quarter: file form 303 showing zero while you remain registered.
- Refund result: only in the last period of the year, except for those on the REDEME.
- Carry-forward balance: can be applied in returns over the four years following the return that generated it.
How to file form 303
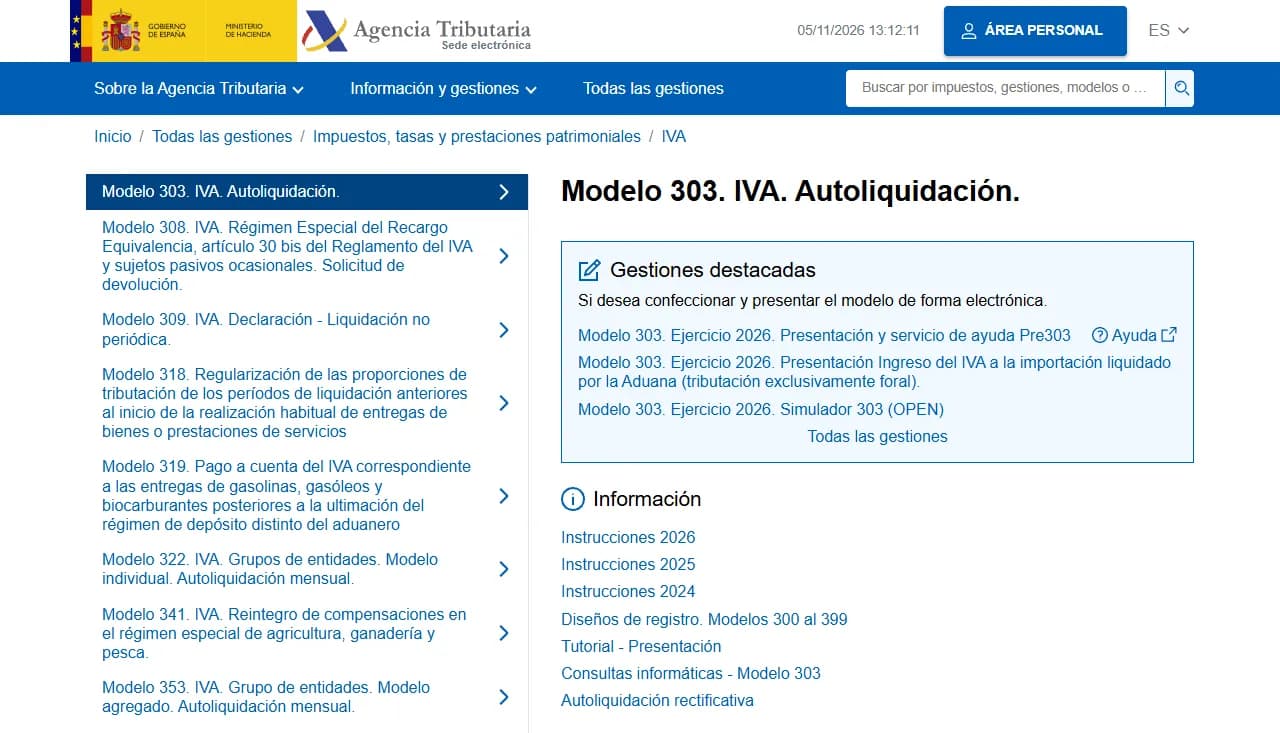
Everything is done online, from the form's page on the Tax Agency's e-office.
- Open the form 303 pageOn the e-office, "Presentación y servicio de ayuda Pre303" opens the form for the current year.
- Identify yourselfWith an electronic certificate, Cl@ve, or as an authorised representative or tax adviser.
- Fill in the boxesTaxable amounts and output VAT, deductible input VAT and, where applicable, amounts carried forward from earlier periods.
- Choose how to payDirect debit (within its deadline), an NRC from your bank or a charge to your account. If the result is a refund or a carry-forward, say so.
- Sign and keep the receiptYou will need the receipt number if you later have to amend the return.
The annual summary: form 390
It covers the whole year and must match the sum of the four 303 returns.
It is filed within the same period as the last 303 of the year: from 1 to 30 January of the following year. It is informative and involves no payment, but mismatches with the quarterly returns are one of the most common reasons for letters from the Tax Agency.
Not everyone has to file it. These are exempt:
- Those who keep their VAT records through the e-office (the Immediate Supply of Information system, SII).
- Quarterly filers taxed only in common territory whose activities are limited to the simplified VAT scheme, urban property rental or both.
Pro-rata: when you mix exempt and taxable supplies
If part of what you invoice is exempt, you can only recover part of the VAT on shared costs.
Under the general pro-rata rule, you deduct the percentage that supplies carrying the right to deduct represent over the total, rounded up to the next whole number.
- Healthcare treatments (exempt)
- €40,000
- Products and courses (not exempt)
- €10,000
- Pro-rata: 10,000 / 50,000
- 20%
- Input VAT on shared costs
- €3,000
- Deductible VAT
- €600
The €2,400 he cannot recover becomes an additional income tax expense.
During the year the provisional pro-rata applies, which is the previous year's final figure. In the last 303 the final pro-rata is calculated and the difference adjusted.
Equivalence surcharge for retailers
Retailers do not file form 303 for that activity: their supplier pays a surcharge on their behalf.
It is compulsory for retailers who are individuals (or entities under income attribution) selling to end consumers without transforming the goods, except for some excluded products. They do not recover input VAT.
| Product VAT rate | Surcharge |
|---|---|
| 21% | 5.2% |
| 10% | 1.4% |
| 4% | 0.5% |
| Tobacco | 1.75% |
- Purchase taxable amount
- €1,000
- VAT at 21%
- €210
- Surcharge at 5.2%
- €52
- Invoice total
- €1,262
When it sells, it charges VAT to customers but does not account for it.
Common mistakes and how to correct them
Nearly all of them are avoided by checking your invoices before closing the quarter.
- Recovering VAT on invoices without your details or on personal expenses.
- Charging 21% on exempt services.
- Forgetting intra-EU acquisitions or services from foreign suppliers.
- Including invoices in the wrong quarter.
Since the third quarter of 2024 (September 2024 for monthly filers), an error in a 303 already filed is corrected with an amending 303 return, whether the outcome is a payment or a refund. You tick the box, give the receipt number of the earlier return and state the reason.
- 1%
- surcharge + 1% per full month of delay
- 15%
- plus late-payment interest after 12 months
- −25%
- off the surcharge if you pay on time
- €0
- penalty if you correct it without a prior request
The VAT calculator helps you check amounts before issuing an invoice, and the tax calendar keeps you from missing a deadline. If you combine activities with different treatment, it is worth having an adviser review them before year end.
Official procedures and pages
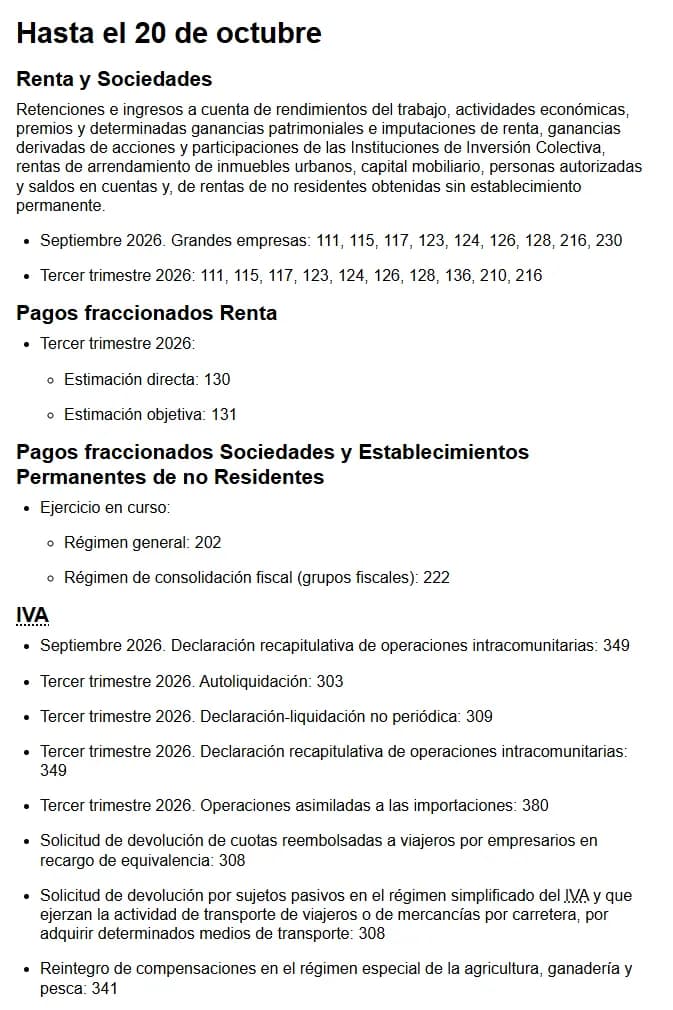
The links you will actually use, all on the Tax Agency's e-office (in Spanish).
Frequently asked questions
Do I have to file form 303 if I have not invoiced anything?
Yes. While you are registered for an activity subject to VAT you must file form 303 each period, even if the result is zero. Only exempt activities and those taxed exclusively under the equivalence surcharge or the special scheme for agriculture, livestock and fishing are excluded.
Can I claim a VAT refund every quarter?
Generally, no. In the first three quarters a negative balance is carried forward and a refund can only be claimed in the fourth. To receive monthly refunds you must join the REDEME (the application is made in November on form 036 for the following year), which requires monthly filing and record-keeping through the SII.
What happens if I file form 303 late?
If there is tax to pay and you file without a prior request, a surcharge of 1% plus 1% for each full month of delay applies; after 12 months it is 15% plus late-payment interest. No penalty is imposed, and the surcharge is cut by 25% if you pay both the tax and the surcharge on time.
Can I recover VAT on my Social Security contribution?
Social Security contributions carry no VAT, so they do not appear on form 303. They are, however, deductible as an income tax expense.
How long do I have to claim VAT I forgot?
You can include it in any later form 303 within four years of the right to deduct arising, provided you have the invoice.
How do I correct a form 303 I have already filed?
Since the third quarter of 2024, with an amending return on the same form: you tick the amendment box, give the receipt number of the earlier return and choose the reason. For earlier periods, the supplementary return or a request for rectification is still used.
Official sources
- Act 37/1992 on Value Added Tax (consolidated text, BOE)
- Act 58/2003, General Tax Act, article 27: late-filing surcharges (BOE)
- Order HAC/819/2024: new form 303 with amending returns (BOE)
- Tax Agency · VAT rates 2026
- Tax Agency · Taxpayer calendar 2026
- Tax Agency · Direct debit deadlines 2026
- VAT practical manual 2026 · Form 303, amending returns
- VAT practical manual 2026 · Who must file form 390
Would you rather we handled it?
Our advisors take care of your paperwork and answer within 24 hours.
Request a free consultation