Spanish income tax 2026: bands, allowances and withholding
The income tax (IRPF) withheld from your payslip is not a random figure: your employer calculates it using a regulated procedure based on your salary, your contributions and what you declare on form 145. But that calculation does not exactly match the tax in your annual return, and that difference produces the amount to pay or to be refunded. Here we explain it with 2026 figures, using Madrid as an example.
The income tax scale: a state portion and a regional portion
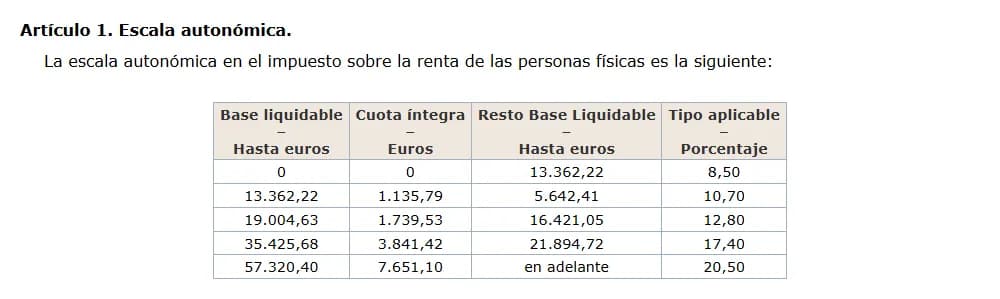
Your tax is the sum of two progressive scales: the state's and your region's.
Income tax on employment income is calculated by applying two scales to the general taxable base: the state scale, which is the same throughout the common territory, and the scale of the region where you live.
Each band only taxes the part of the base that falls within it. That is why earning more never leaves you worse off in net terms because you "jump" a band.
| Taxable base | State | Madrid | Total in Madrid |
|---|---|---|---|
| Up to €12,450 | 9.5% | 8.5% | 18% |
| €12,450 – €13,362.22 | 12% | 8.5% | 20.5% |
| €13,362.22 – €19,004.63 | 12% | 10.7% | 22.7% |
| €19,004.63 – €20,200 | 12% | 12.8% | 24.8% |
| €20,200 – €35,200 | 15% | 12.8% | 27.8% |
| €35,200 – €35,425.68 | 18.5% | 12.8% | 31.3% |
| €35,425.68 – €57,320.40 | 18.5% | 17.4% | 35.9% |
| €57,320.40 – €60,000 | 18.5% | 20.5% | 39% |
| €60,000 – €300,000 | 22.5% | 20.5% | 43% |
| Over €300,000 | 24.5% | 20.5% | 45% |
From gross salary to taxable base
You subtract your contributions, €2,000 of expenses and, on low pay, an extra reduction.
- Start from annual gross paySalary, extra payments and benefits in kind: this is your gross employment income.
- Subtract your contributionsIn 2026, on a permanent contract, employees contribute 6.50%: 4.70% common contingencies, 1.55% unemployment, 0.10% vocational training and 0.15% for the intergenerational equity mechanism (MEI).
- Subtract €2,000 of other expensesA fixed amount. It rises to €4,000 with geographical mobility, and there are higher amounts for workers with disabilities.
- Apply the employment income reductionOnly if your net income (gross less contributions) is below €19,747.50.
| Net income | Reduction |
|---|---|
| Up to €14,852 | €7,302 |
| €14,852 to €17,673.52 | €7,302 − 1.75 × (income − 14,852) |
| €17,673.52 to €19,747.50 | €2,364.34 − 1.14 × (income − 17,673.52) |
| From €19,747.50 | No reduction |
The personal and family allowance
The part of your income considered necessary to live on, which in practice is not taxed.
The allowance is not deducted from the base. Tax is calculated on the whole base and then the tax that would correspond to the allowance is subtracted, applying the first bands of the scale.
| Item | State | Madrid |
|---|---|---|
| Taxpayer | €5,550 | €5,956.65 |
| Over 65 (additional) | €1,150 | €1,234.26 |
| Over 75 (additional) | €1,400 | €1,502.58 |
| First child | €2,400 | €2,575.85 |
| Second child | €2,700 | €2,897.83 |
| Third child | €4,000 | €4,400 |
| Fourth and subsequent | €4,500 | €4,950 |
| Each child under 3 (additional) | €2,800 | €3,005.16 |
- Children qualify if they are under 25 (or have a disability), live with you and have annual income of no more than €8,000.
- If both parents qualify, each applies half.
- There are also allowances for parents over 65 who live with you and for disability.
Full example: €30,000 gross in Madrid
A single employee with no children and a permanent contract.
- Annual gross salary
- €30,000
- Contributions (6.50%)
- − €1,950
- Other expenses
- − €2,000
- Employment income reduction
- €0
- Taxable base
- €26,050
There is no reduction because net income (€28,050) exceeds €19,747.50.
- State scale on €26,050
- €2,990.25
- Less state scale on the allowance (€5,550)
- − €527.25
- Madrid scale on €26,050
- €2,641.34
- Less Madrid scale on the allowance (€5,956.65)
- − €506.32
- Total income tax for the year
- €4,598.02
- 15.33%
- average rate on gross salary
- 27.8%
- marginal rate: what each extra euro pays
How your employer calculates payroll withholding
It uses its own scale, the same across the common territory, and spreads the result over every payment.
Your employer does not apply your region's scale. It uses the withholding scale of 19%, 24%, 30%, 37%, 45% and 47%, in the same bands as the state scale: in effect, the state scale doubled with a 47% cap.
- Work out the withholding baseAlmost the same as the taxable base: gross pay less contributions, other expenses and reductions.
- Apply the withholding scaleTo the base and, separately, to the personal and family allowance.
- Subtract one from the otherThe result is the annual withholding amount.
- Divide by annual payThe rate is truncated to two decimals and applied to every payment, including extra ones.
- Withholding scale on €26,050
- €5,980.50
- Less scale on the allowance (€5,550)
- − €1,054.50
- Withholding amount
- €4,926
- Rate: 4,926 / 30,000
- 16.42%
With 14 payments of €2,142.86, each payslip carries €351.86 of income tax. The 12 ordinary ones also carry €162.50 in contributions.
There are two safeguards. If your pay does not exceed a threshold that depends on your family situation, nothing is withheld. And for salaries up to €35,200, withholding cannot exceed 43% of the difference between your pay and that threshold.
| Situation | No children | 1 child | 2 or more |
|---|---|---|---|
| Single-parent family | — | €17,644 | €18,694 |
| Spouse with income up to €1,500 | €17,197 | €18,130 | €19,262 |
| All other cases | €15,876 | €16,342 | €16,867 |
Form 145 and adjustments during the year
What you tell your employer sets your withholding; if something changes, it is recalculated.
Form 145 is how you tell your employer about your family situation. It is not filed with the Tax Agency: you hand it to whoever pays you.
- Family situation and your spouse's tax ID, if relevant.
- Children and parents who live with you.
- Disability, yours or your relatives'.
- Court-ordered maintenance or child support payments.
- Payments on a loan for a main home bought before 2013 (cuts withholding by 2 points if you earn less than €33,007.20).
When circumstances change, your employer adjusts: it recalculates the rate with the new details and offsets what has already been withheld in the remaining payslips. This is common after a pay rise, the birth of a child or the extension of a temporary contract.
The minimum wage credit: why the minimum wage pays no income tax
A credit in the annual return brings the tax to zero for minimum wage earners.
- €1,221
- monthly minimum wage over 14 payments (€17,094 a year)
- €590.89
- maximum credit in 2026
- €20,048.45
- the credit disappears from here
The credit is €590.89 if your gross employment income does not exceed €17,094. Above that, it falls by 20 cents for each additional euro until it disappears at €20,048.45.
It only applies to pay from an employment or civil service relationship, if you have no other income (excluding exempt income) above €6,500, and it can never exceed the tax attributable to that pay.
- Minimum wage (€17,094): 3.06% withheld
- €523
- Minimum wage: final tax after the credit
- €0
- Minimum wage: refund in the return
- €523
- €18,500: 6.09% withheld
- €1,127
- €18,500: final tax after a €309.69 credit
- €866
- €18,500: refund in the return
- €260
Payroll ignores this credit: it is applied when you file your return.
Why your return shows an amount to pay or a refund
The return compares the actual tax for the year with what was withheld.
In Madrid, because the regional scale is lower than the withholding scale, the normal result for an employee with a single payer is a small refund.
| Gross salary | Withheld on payroll | Actual tax | Refund |
|---|---|---|---|
| €30,000 | €4,926 (16.42%) | €4,598 | €328 |
| €45,000 | €9,473 (21.05%) | €8,881 | €591 |
| €60,000 | €14,664 (24.44%) | €13,916 | €748 |
These are the most common reasons the result changes:
- Two or more payers: each employer withholds as if it were your only income, so you usually end up paying.
- Changes you did not report on form 145, such as a separation or a child no longer qualifying for the allowance.
- Other income without enough withholding: rental income, gains on selling funds or shares, or self-employed work.
- Reductions and credits not reflected in payroll: pension plans, donations, the minimum wage credit or Madrid's regional credits, such as those for renting a home or the birth of a child.
| Your case | Must you file? |
|---|---|
| One payer | Only if your employment income exceeds €22,000 |
| Several payers, with the second and others adding up to more than €1,500 | From €15,876 |
| You were registered as self-employed at any point in the year | Always |
Official procedures and pages
Where to calculate your withholding, download form 145 and check the law (in Spanish).
Frequently asked questions
Does withholding depend on the region where I live?
No. The withholding scale is the same throughout the common territory. Your region only affects the annual return, which is why in regions with lower scales, such as Madrid, a refund is common.
Can I ask my employer to withhold more?
Yes. You can request in writing a higher withholding rate than the calculated one. It is advisable if you have two payers, let out a property or want to avoid a large payment when you file.
Why is income tax withheld if I earn the minimum wage?
Because withholding does not take the minimum wage credit into account; it is applied in the annual return. If that salary is your only income, the amount withheld will be refunded when you file, so it is worth filing even if you are not required to.
How much does having children lower withholding?
It depends on the salary. On €30,000 gross with two children whose allowance is shared with the other parent, the rate falls from 16.42% to 14.80%, about €486 less withheld per year.
Where do I file form 145?
It is not filed with the Tax Agency: you hand it to your employer or payer, who keeps it. The Tax Agency only publishes the form for download.
Official sources
- Act 35/2006 on Personal Income Tax (consolidated text, BOE)
- Royal Decree 439/2007, Income Tax Regulations (consolidated text, BOE)
- Community of Madrid Legislative Decree 1/2010 on ceded taxes (consolidated, BOE)
- Royal Decree-law 5/2026: new employment income credit amounts (BOE)
- Royal Decree 126/2026: 2026 minimum wage (BOE)
- Tax Agency · 2026 withholding algorithm and calculator
- Social Security · Contribution bases and rates 2026
- Tax Agency · Who must file, 2025 return
Would you rather we handled it?
Our advisors take care of your paperwork and answer within 24 hours.
Request a free consultation