Spain's 2026 tax calendar for the self-employed and SMEs: key dates
The Tax Agency's taxpayer calendar lists hundreds of deadlines, but a typical self-employed person or SME only needs to master about a dozen. Here we go through them form by form with the official 2026 dates, how they move when they fall on a non-working day and what is left to do before the year ends.
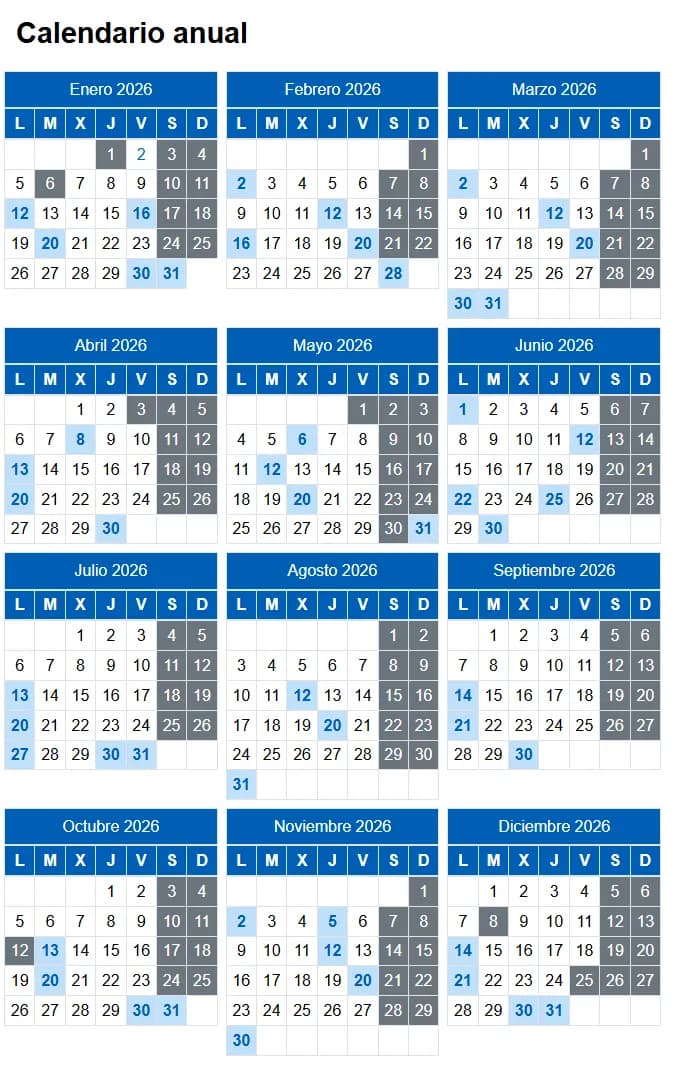
How to read the calendar: periods and working days
Quarterly returns in April, July, October and January; annual ones in January, February and summer.
Obligations are grouped by frequency. Quarterly returns are filed in the first twenty days of the month after the quarter, except the fourth: VAT and income tax instalments have until 30 January.
Annual information returns are concentrated in January and February, and corporate and personal income tax returns in spring and summer. The window normally opens on the 1st of the month, so there is no need to wait until the last day.
| Normal deadline | Day of the week in 2026 | Moved to |
|---|---|---|
| 31 January (annual summaries 190, 180…) | Saturday | Monday 2 February |
| 28 February (form 347) | Saturday | Monday 2 March |
| 25 July (form 200) | Saturday | Monday 27 July |
| 12 October (September Intrastat) | National Day | Tuesday 13 October |
| 20 December (form 202) | Sunday | Monday 21 December |
Quarterly returns: 303, 130, 111 and 115
They are the core of any self-employed person's calendar.
| Form | What it is | Who files it |
|---|---|---|
| 303 | VAT return: output VAT less deductible input VAT. | Almost all self-employed people and companies with VAT-able activity. |
| 130 | Income tax instalment: 20% of year-to-date net income, less withholding and earlier payments. | Self-employed people under direct assessment (under the module system, form 131). |
| 111 | Withholding on employees and professionals. | Anyone with employees or paying invoices with withholding. |
| 115 | Withholding on business premises rent (19% of the rent). | Anyone renting premises from a landlord subject to withholding. |
| Quarter | Filing | With direct debit |
|---|---|---|
| Q4 2025 | 111 and 115: by 20 January · 303 and 130: by 30 January | By 15 January (111, 115) and 27 January (303, 130) |
| Q1 2026 | By 20 April | By 15 April |
| Q2 2026 | By 20 July | By 15 July |
| Q3 2026 | By 20 October | By 15 October |
| Q4 2026 | 111 and 115: by 20 January · 303 and 130: by 1 February 2027 | To be set in the 2027 calendar |
What is left of 2026: November and December
Few deadlines, but with decisions that affect all of 2027.
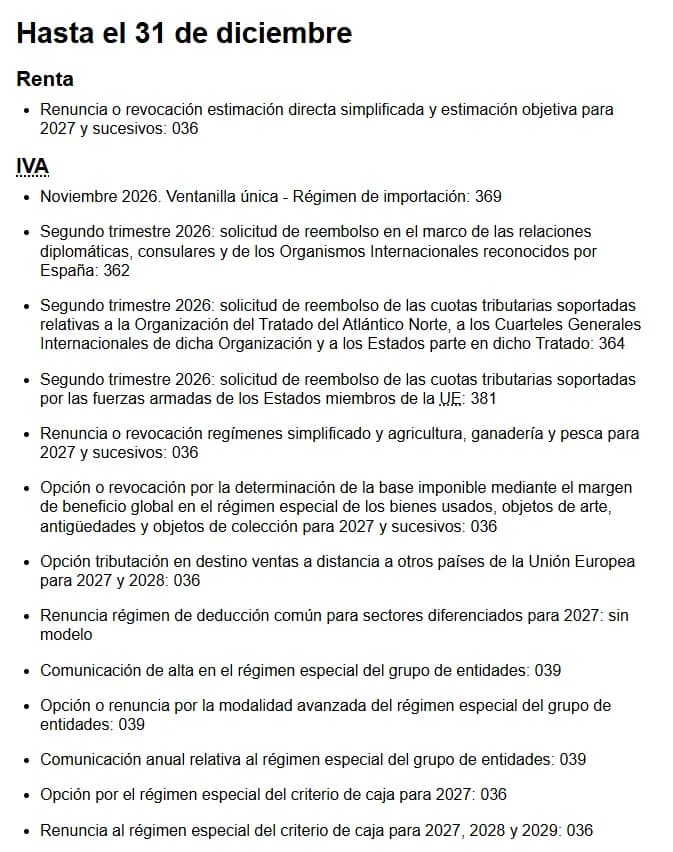
The busy part of the autumn is over: the third quarter closed on 20 October, and on 5 November the second instalment of the 2025 income tax return was collected from those who split it. Little remains, but December is the time to review choices for 2027.
| Date | What is due | Who it affects |
|---|---|---|
| 30 November | October form 303 · Joining or leaving the monthly refund register (REDEME) on form 036 · Opting out of the SII | Monthly VAT filers, or those who want to file monthly in 2027 |
| 21 December | Third corporate tax instalment (form 202) | Companies |
| 30 December | November form 303 | Monthly VAT filers |
| 31 December | Waiving or revoking simplified direct assessment, the module system and the simplified VAT scheme · Opting into or out of the cash accounting scheme (form 036) | Self-employed people who want to change scheme in 2027 |
- 20 October: Q3 forms 303, 130 and 115
- Filed
- 5 November: second instalment of the 2025 return
- Collected
- Before 31 December
- Cash accounting in 2027?
She invoices with withholding and rents her studio, which is why she files form 115. Under cash accounting she would not pay over the VAT on her invoices until she is paid.
Annual summaries in January and February: 390, 190, 180 and 347
No payment is involved, but the Tax Agency cross-checks them with your clients' and suppliers' returns.
| Form | What it summarises | 2026 deadline | Expected 2027 deadline |
|---|---|---|---|
| 390 | VAT for the whole year | 30 January | 1 February (30 January is a Saturday) |
| 190 | Withholding on employees and professionals (forms 111) | 2 February | 1 February (31 January is a Sunday) |
| 180 | Withholding on rent (forms 115) | 2 February | 1 February (31 January is a Sunday) |
| 347 | Clients and suppliers above €3,005.06 in the year, VAT included | 2 March | 1 March (28 February is a Sunday) |
Form 347 is not filed by those keeping their records through the SII nor, generally, by those under the module system for that activity.
Corporate tax: forms 200 and 202
One annual return in July and three instalments in April, October and December.
Companies file form 200 within 25 calendar days after the six months following the end of the tax year. For a 31 December year end the deadline is 25 July; in 2026 that was a Saturday, so it moved to the 27th (with direct debit, the 22nd).
| Instalment (202) | Deadline | With direct debit |
|---|---|---|
| First | 20 April | 15 April |
| Second | 20 October | 15 October |
| Third | 21 December | 16 December |
- Last year's gross tax, less credits, allowances and withholding
- €12,000
- Percentage
- 18%
- Each instalment
- €2,160
The personal income tax return
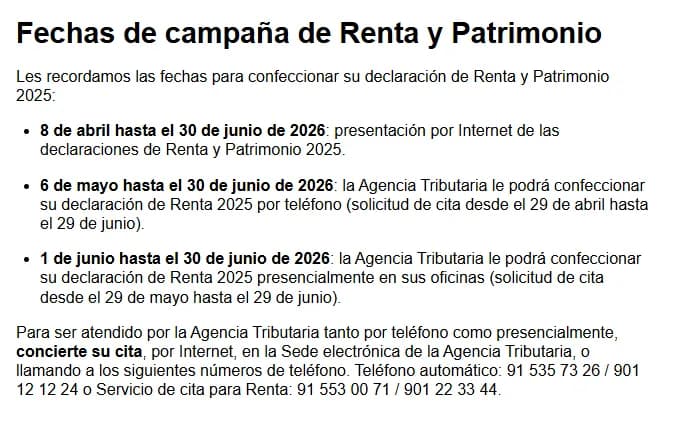
The 2025 income tax campaign ran from 8 April to 30 June 2026.
| Step | Dates in 2026 |
|---|---|
| Online filing | 8 April to 30 June |
| Telephone service (by appointment) | 6 May to 30 June |
| In-person service at offices (by appointment) | 1 to 30 June |
| Amount payable by direct debit | By 25 June |
| Second instalment, if split (form 102) | 5 November |
Payment can be split into two interest-free instalments: 60% when filing and the remaining 40% by 5 November, the last income tax date of 2026. The 2026 return, including this year's business income, will be filed in spring 2027.
Direct debit and payment methods
Direct debit is convenient, but it shortens the filing window.
With direct debit you file and forget: the payment is collected on the last day of the period. In exchange, the filing window is shorter. For the April, July and October quarterly returns it ends on the 15th; in January, forms 303 and 130 can be paid by direct debit until the 25th (the 27th in 2026).
- Up to the 15th: direct debitYou file and choose a charge to your account. The payment is collected on the last day of the period.
- From the 16th to the 20th: NRC or account chargeAsk your bank for a full reference number (NRC) or pay by account charge from the e-office.
- If you cannot payFile on time anyway and request a deferral or instalments. Filing late carries a surcharge; not filing is worse.
How to stay on top of every deadline
A monthly close and two reminders per quarter are enough.
- Record issued and received invoices every month: the quarter is then ready in an afternoon.
- Set a reminder on the 10th of the filing month to review the figures.
- Set another on the 15th if you pay by direct debit.
- At the end of December, check the 2027 calendar once the Tax Agency publishes it.
The interactive tax calendar on our website lists every 2026 date filtered by type of taxpayer, and your adviser can file each form on time for you.
Official procedures and pages
The official calendar and each form's page on the Tax Agency e-office (in Spanish).
Frequently asked questions
What happens if the last day falls on a weekend or public holiday?
The deadline automatically moves to the next working day. For example, 20 December 2026 is a Sunday, so the corporate tax instalment can be filed until Monday the 21st.
Do I have to file all these forms?
No. A self-employed professional with no employees or rented premises usually files only form 303 and, unless the 70% withholding exception applies, form 130, plus form 390 and the annual income tax return. Forms 111, 115, 190 and 180 are only filed if you withhold tax, and forms 200 and 202 are for companies.
Can I file a form before the period opens?
Not before the filing period opens, which usually starts on the 1st of the month. Within the period you can file on the first day and choose direct debit so the payment is taken at the end.
What happens if I file late?
If you do so voluntarily and there is tax to pay, you will pay a surcharge of 1% plus 1% for each full month of delay; after 12 months, 15% plus late-payment interest. If the Tax Agency asks you first, a penalty may apply.
Which tax deadlines are left for the rest of 2026?
If you file quarterly as self-employed, none until January, except elections and waivers taking effect in 2027, which close on 31 December. Companies have the third instalment on 21 December, and monthly VAT filers have October's form 303 on 30 November and November's on 30 December.
When is the fourth quarter of 2026 filed?
Forms 111 and 115 by 20 January 2027. Forms 303 and 130 and the annual summary 390 by 30 January, which in 2027 is a Saturday, so the deadline moves to Monday 1 February.
Official sources
- Tax Agency · Taxpayer calendar 2026
- Tax Agency · Direct debit deadlines 2026
- Tax Agency · Deadlines on non-working days, Saturdays and holidays
- Tax Agency · 2025 income and wealth tax campaign dates
- Act 27/2014 on Corporate Income Tax, articles 40 and 124 (BOE)
- Act 58/2003, General Tax Act, article 27: surcharges (BOE)
Would you rather we handled it?
Our advisors take care of your paperwork and answer within 24 hours.
Request a free consultation