How to Register as Self-Employed in Spain in 2026: Step by Step
Registering as self-employed in Spain involves two separate steps: one with the Tax Agency and one with Social Security. Both are done online and must be completed before you start working. Here they are in order, with the contribution figures in force in 2026 and the mistakes we see most often in the first few months.
Before you start: three decisions
Get your details ready before opening the forms and registration will take an afternoon.
Your start date is the day you begin offering your services or buying goods to sell, not the day you are first paid. That date governs both registrations.
Decide too whether you will work as an individual or through a company. This guide covers individuals; if you are unsure, see our comparison of sole trader and limited company.
- Planned start date of the activity.
- A precise description of what you will do, to choose the right IAE heading and CNAE code.
- Business address and, if you work from home, the part of the property you will use.
- A reasonable forecast of first-year income and expenses, to choose your contribution base.
- A bank account for direct debits of contributions and taxes.
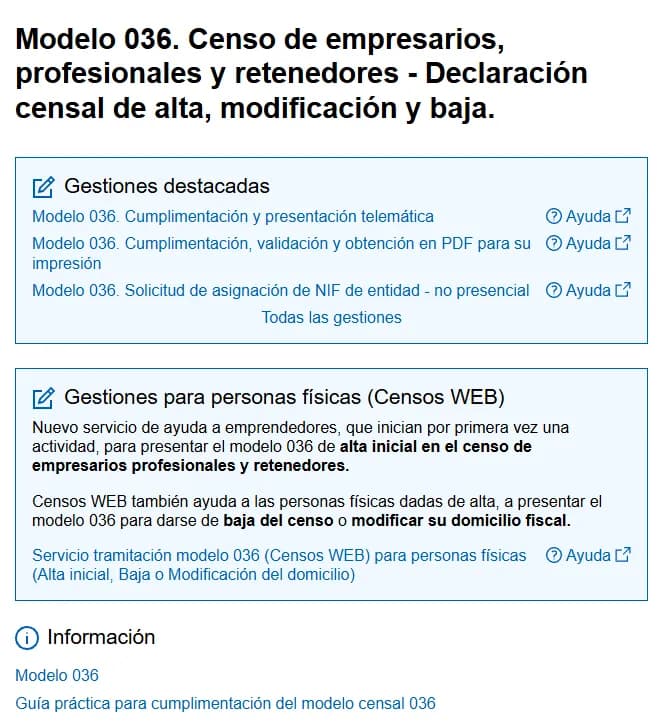
Step 1: tax registration with form 036
The census return is filed before you start trading.
Form 036 is now the only registration form. The old simplified form 037 was abolished by Order HAC/1526/2024 with effect from 3 February 2025. Form 036 now includes a wizard that only shows the boxes that apply to you.
- Personal details and start dateYour tax ID (NIF), tax address and the actual date you start.
- Activity and IAE headingOne line per activity, with its heading and the address where you carry it out.
- Income tax regimeWhen starting out this is usually simplified direct assessment, which applies if your turnover does not exceed €600,000 a year and you do not opt out.
- VAT regimeThe general regime, unless your activity is exempt or you are a retailer under the equivalence surcharge.
- Home use, if you work from homeState the percentage of the property used for the business: it is the basis for deducting part of its costs later.
Step 2: choose the right IAE heading
Among other things, the heading determines the withholding on your invoices.
The Business Activities Tax (IAE) classifies each activity under a heading. Individuals are exempt from paying it, but must still register under the correct heading through form 036.
| Type of activity | IAE section | Withholding on invoices to businesses and self-employed clients |
|---|---|---|
| Business (retail, hospitality, trades…) | First | As a rule, no |
| Professional (consulting, design, law…) | Second | Yes: 15% standard or 7% in the first years |
If you carry out several activities, register under every heading. A mistake can be corrected with an amending form 036, but in the meantime it can lead to the wrong withholding or VAT treatment.
Step 3: RETA registration through Import@ss
Apply before you start, no more than 60 days in advance.
The second step is registering with the special scheme for self-employed workers (RETA) on Import@ss, the online portal of the General Treasury of Social Security.
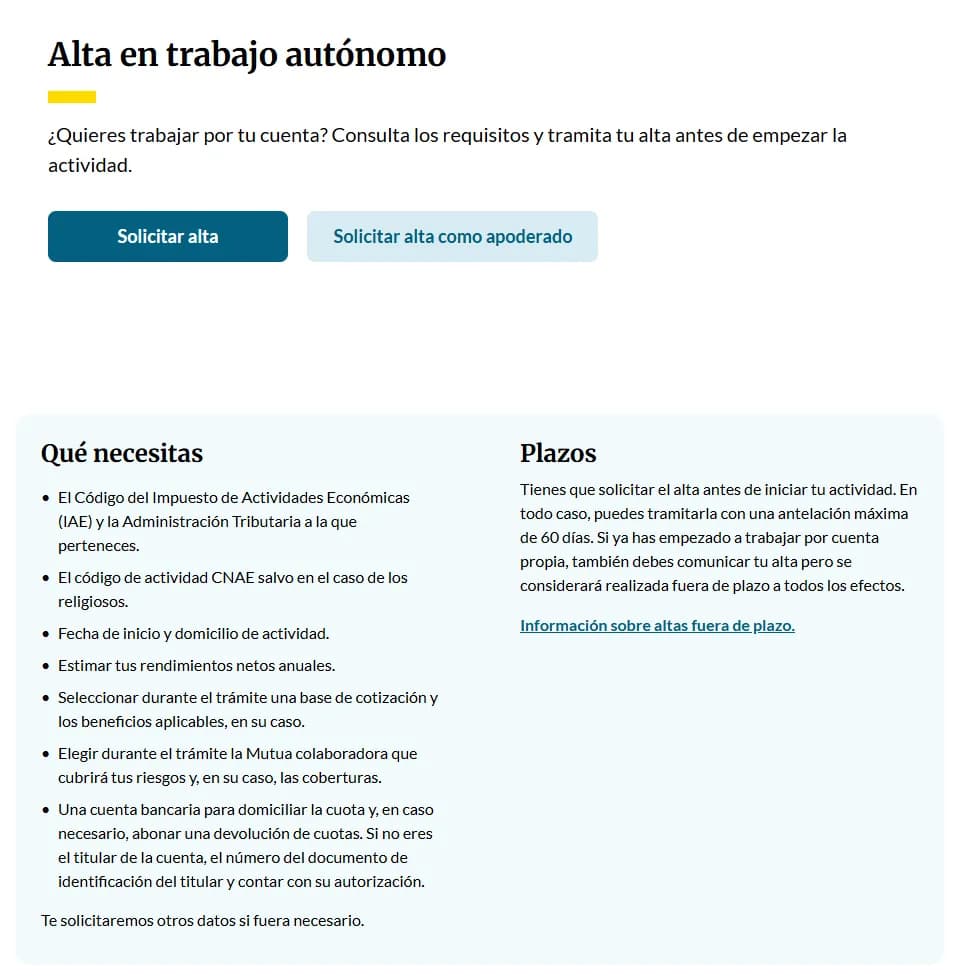
- Open «Alta en trabajo autónomo»Using a certificate, electronic ID or Cl@ve.
- Enter activity, CNAE code and start dateThe date must match the one on form 036.
- Estimate your net earningsThis forecast determines your band and contribution base.
- Request the flat rate, if eligibleIt is not applied automatically: you request it in the registration itself.
- Choose a mutual insurer and bank accountThe mutual insurer covers temporary incapacity and occupational risks.
Each month's contribution is direct-debited on the last working day of that same month.
The €80 flat rate
Twelve months at a reduced rate, extendable by twelve more if you earn less than the minimum wage.
The reduced contribution for new self-employed workers is set out in Article 38 ter of Law 20/2007, the Self-Employed Workers' Statute. It is €80 a month for the 12 full calendar months following registration, regardless of your income.
- €80
- a month for the first 12 months
- +12 months
- extension if your earnings are below the minimum wage
- €17,094
- annual minimum wage in 2026 (€1,221 in 14 payments)
- It is for people registering for the first time or who have not been self-employed in the previous two years (three if they have had it before).
- You request it when registering. The extension is requested in Import@ss before the second period starts, declaring that your earnings will be below the minimum wage.
- It does not apply to family members working with a self-employed relative.
- With a disability of 33% or more, or for victims of gender violence or terrorism, the periods are 24 and 36 months.
- Flat rate
- €80/month until 30-9-2027
- Expected first-year turnover
- €30,000
- Business expenses
- − €6,000
- Net earnings
- €24,000
- Below the minimum wage (€17,094)?
- No: no extension
When the flat rate ends she will pay according to her band: €24,000 × 0.93 / 12 = €1,860 a month, band 8, with a minimum contribution of €380.88 under the 2026 tables.
How to choose your contribution base
You contribute according to your actual net earnings, adjusted the following year.
You declare a forecast of monthly net earnings and choose a base within your band. The following year Social Security checks your figures with the Tax Agency and refunds or claims the difference.
- Annual income
- €36,000
- Deductible expenses (excluding your own contribution)
- − €8,000
- Net earnings
- €28,000
- 7% allowance for general expenses
- − €1,960
- Computable earnings
- €26,040
- Per month (divided by 12)
- €2,170 → band 9
Band 9: minimum base of €1,274.51 and minimum contribution of €401.47 a month. For partners in trading companies the allowance is 3%.
| Band | Monthly net earnings | Minimum base | Minimum contribution |
|---|---|---|---|
| 1 | Up to €670 | €653.59 | €205.88 |
| 2 | €670.01 to €900 | €718.95 | €226.47 |
| 3 | €900.01 to €1,166.69 | €849.67 | €267.65 |
| 4 | €1,166.70 to €1,300 | €950.98 | €299.56 |
| 5 | €1,300.01 to €1,500 | €960.78 | €302.65 |
| 6 | €1,500.01 to €1,700 | €960.78 | €302.65 |
| 7 | €1,700.01 to €1,850 | €1,143.79 | €360.29 |
| 8 | €1,850.01 to €2,030 | €1,209.15 | €380.88 |
| 9 | €2,030.01 to €2,330 | €1,274.51 | €401.47 |
| 10 | €2,330.01 to €2,760 | €1,356.21 | €427.21 |
| 11 | €2,760.01 to €3,190 | €1,437.91 | €452.94 |
| 12 | €3,190.01 to €3,620 | €1,519.61 | €478.68 |
| 13 | €3,620.01 to €4,050 | €1,601.31 | €504.41 |
| 14 | €4,050.01 to €6,000 | €1,732.03 | €545.59 |
| 15 | Over €6,000 | €1,928.10 | €607.35 |
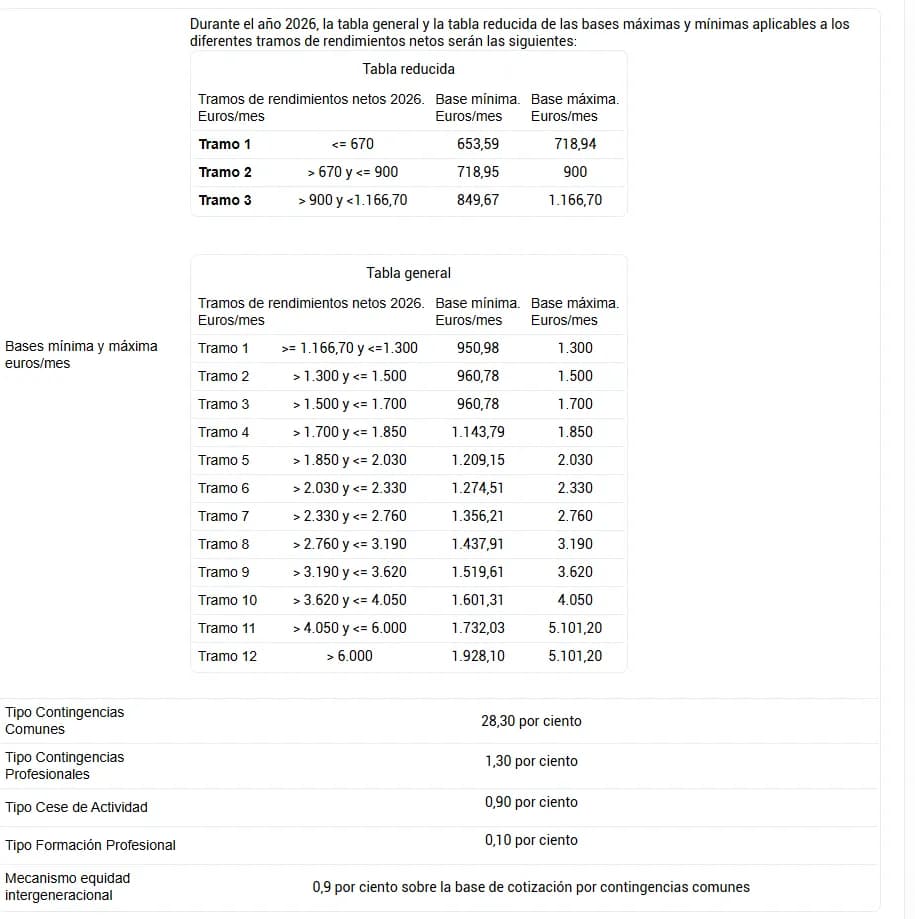
- 31.50%
- total rate in 2026 (including 0.9% MEI)
- 6
- base changes a year at most
- 7%
- general expenses allowance (3% for company partners)
If your forecast changes, you can change your base up to six times a year. The change takes effect on 1 March, May, July, September or November, or on the following 1 January, depending on when you apply.
Obligations from day one
Complete invoices, up-to-date records and quarterly returns.
- Consecutive numbering and date.
- Your details and your client's, with tax IDs.
- Description of the service, taxable base, VAT rate and amount.
- Income tax withholding if you are a professional invoicing businesses or self-employed clients.
| Form | What it is | When |
|---|---|---|
| 303 | Quarterly VAT return | Every quarter, even if you have not invoiced |
| 130 | Income tax instalment under direct assessment | Every quarter, unless at least 70% of last year's income was subject to withholding |
| 111 | Withholding on employees and professionals | If you hire staff or pay professionals |
| 115 | Withholding on rented business premises | If you rent premises for the business |
| 390 | Annual VAT summary | In January, unless you are exempt |
| 100 | Annual income tax return | In spring |
You must also keep records of income, expenses and capital goods, and keep the invoices you receive.
Common mistakes in the first months
Most are avoided with a little organisation at the start.
- Invoicing before you are registered, or registering with the Tax Agency and forgetting Social Security.
- Not requesting the flat rate when registering.
- Charging VAT on exempt services, or not charging it on those that are not exempt.
- Not setting money aside for quarterly taxes.
If you start in the last quarter of the year, your first returns are due in January, together with the annual VAT summary. Plan that first year-end in good time or ask an adviser to check your registration before you file it.
Frequently asked questions
Do I register with the Tax Agency or Social Security first?
Usually form 036 first and then RETA registration, because Import@ss asks for your IAE heading. Both must be completed before you start working.
Does form 037 still exist?
No. Order HAC/1526/2024 abolished it with effect from 3 February 2025. All census registrations, changes and deregistrations are now filed on form 036.
How far in advance can I register with Social Security?
Up to 60 calendar days before you start. If you apply once you have already started, it is processed but treated as late for all purposes.
Can I be registered only in the months I work?
You must be registered while you carry out the activity on a regular basis. Several registrations and deregistrations a year are allowed, but they are not a way to contribute only when you invoice if the activity continues.
What happens if my actual earnings differ from my forecast?
The following year Social Security receives your actual earnings from the Tax Agency and adjusts: if you paid below your band it claims the difference, and if you paid above it refunds the excess.
How much will I pay when the flat rate ends?
It depends on your net earnings. With the 2026 tables and the 31.50% rate, the minimum contribution ranges from €205.88 a month in the lowest band to €607.35 in the highest. The self-employed contribution calculator gives you an estimate with your figures.
Official sources
- Import@ss: self-employed registration
- Social Security: contribution bases and rates 2026
- Social Security: new contribution system for the self-employed
- Spanish Tax Agency: form 036
- Law 20/2007, Self-Employed Workers' Statute (Art. 38 ter)
- Order PJC/297/2026 on contributions for 2026
- Royal Decree-law 3/2026 (2025 tables carried over)
- Royal Decree 126/2026, minimum wage for 2026
- Order HAC/1526/2024 (abolition of form 037)
- Royal Decree-law 15/2025 (Verifactu deadlines)
- Spanish Tax Agency: invoicing software (Verifactu)
- Law 35/2006 on Personal Income Tax (withholding on professional income)
Would you rather we handled it?
Our advisors take care of your paperwork and answer within 24 hours.
Request a free consultation