Deductible Expenses for the Self-Employed in Spain: A Guide
Deducting your expenses properly is the most direct and legal way to pay less tax as a self-employed person in Spain. It is also what the Tax Agency scrutinises most closely. Here are the requirements, the most disputed cases with figures, and why the same expense can be deductible for income tax but not for VAT, or the other way round.
Three requirements for every expense
If just one fails, the Tax Agency can reject the expense on review.
Under direct assessment, standard or simplified, your profit is what you earn minus the expenses needed to earn it. For an expense to count, three conditions must be met at once.
- Business useThe expense is linked to the activity you declared on form 036 and is needed for it.
- EvidenceA full invoice with your name and tax ID (NIF). An anonymous till receipt is weak evidence.
- Recording and timingEntered in your expenses or capital goods record, in the year it belongs to.
Expenses that are almost always deductible
If properly documented, they rarely raise questions.
- Your self-employed contributions, including the flat rate, in full for income tax.
- Rent of business premises or an office.
- Accountant and adviser fees.
- Charges on the business bank account.
- Software, professional subscriptions and advertising.
- Office supplies and stock purchases.
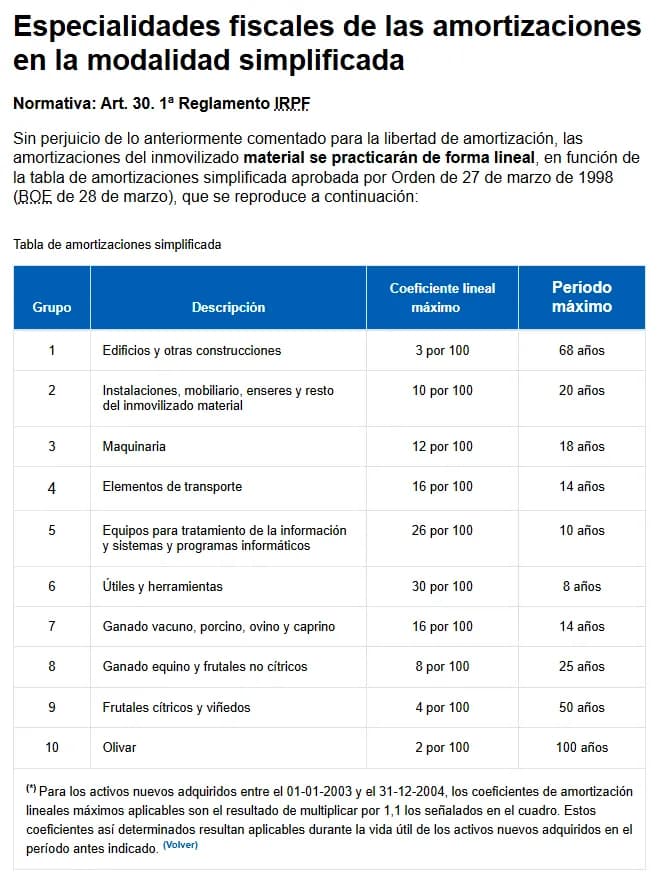
Capital goods, such as a computer, a vehicle or furniture, are not deducted all at once: they are depreciated over their useful life. Under simplified direct assessment you use the simplified table.
| Asset | Maximum annual rate | Maximum period |
|---|---|---|
| Computer equipment and software | 26% | 10 years |
| Tools and implements | 30% | 8 years |
| Vehicles | 16% | 14 years |
| Furniture and fittings | 10% | 20 years |
| Buildings and other structures | 3% | 68 years |
- Income
- €40,000
- Documented expenses
- − €12,000
- Net profit before allowance
- €28,000
- 5% hard-to-document allowance (max. €2,000)
- − €1,400
- Net profit
- €26,600
No invoice needed: it is applied to the profit after all other expenses.
Working from home: property and utilities
The part of your home used for business opens the door to deducting its costs.
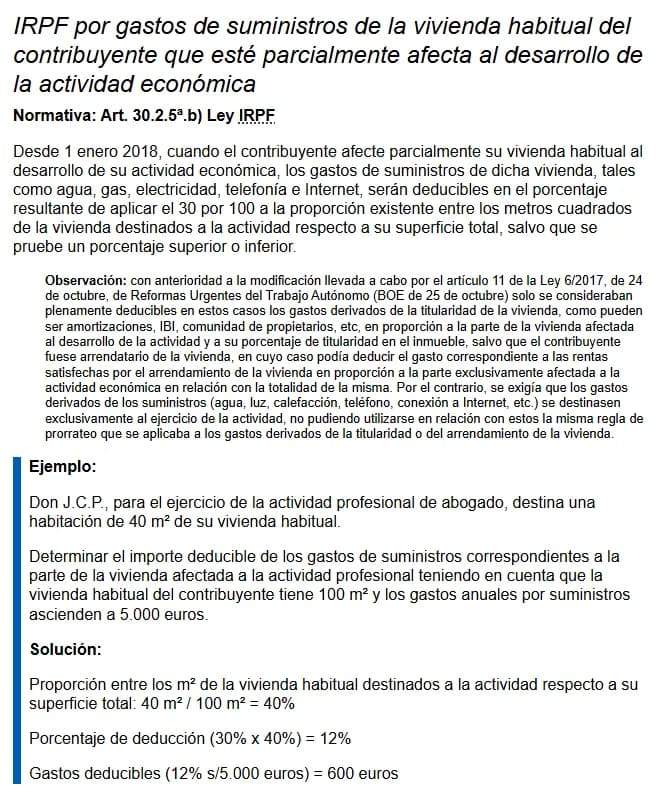
If you work from home and have declared the business share on form 036, you deduct that proportion of the property costs: rent, council tax (IBI), community fees, home insurance or, if you own it, depreciation of the building. The share is normally calculated by floor area.
Utilities have their own rule in Article 30.2.5.b of the Income Tax Law: you deduct 30% of the business share, unless you can prove a different percentage.
- Business share: 18 / 90
- 20%
- Rent: €900 × 12 months × 20%
- €2,160
- Utilities: €1,800 × 20% × 30%
- €108
- Total deductible for income tax
- €2,268
This amounts to deducting 6% of each electricity, water, gas, phone and internet bill.
Vehicles: the big difference between income tax and VAT
What is almost impossible for income tax is half presumed for VAT.
| Income tax | VAT | |
|---|---|---|
| Car used privately as well | Not deductible: exclusive use required | Presumed 50% business use |
| Mixed-use vehicle for carrying goods | Deductible if used only for the business | Presumed 100% business use |
| Sales agents, transport, driving schools, hire | Deductible even with some private use | Presumed 100% business use |
| Burden of proof | On you, for exclusive use | On you, to deduct more than 50% |
For income tax a car only counts as a business asset if it is used exclusively for the business. A Saturday trip to the supermarket is enough to lose the deduction, except in the cases listed in the regulations.
- Lease payments: €450 × 12 months
- €5,400
- Deductible for income tax (exclusive use)
- €5,400
- Input VAT: €5,400 × 21%
- €1,134
- Deductible on form 303 (100% presumption)
- €1,134
With a car also used privately, by contrast, he could deduct nothing for income tax and, as a rule, only €567 of VAT (50%).
Meals and travel expenses
Meals are deductible up to a cap and only outside your town.
Your own meals are deductible if they are in restaurants or hospitality venues, paid electronically and in a municipality other than the one where you live and the one where you work.
| Trip | In Spain | Abroad |
|---|---|---|
| No overnight stay | €26.67 a day | €48.08 a day |
| With overnight stay | €53.34 a day | €91.35 a day |
- Lunch paid by card
- €35.00
- Daily limit without overnight stay in Spain
- €26.67
- Deductible for income tax
- €26.67
Accommodation, tickets, tolls and parking on business trips are deductible at their actual cost if you have an invoice and can show the reason for the trip. Keep a note of the client or event.
Insurance, training and what is never deductible
Health insurance is capped, and there is a short list of banned expenses.
| Insurance | Limit |
|---|---|
| Health cover for you, your spouse and children under 25 living with you | €500 per person per year |
| Health cover for people with disabilities | €1,500 per person per year |
| Professional liability, premises, machinery | No specific limit |
Training is deductible when it relates to your activity: a digital tax course for an adviser fits; a master's degree unrelated to what you invoice is unlikely to be accepted. The same applies to books, conferences and professional body fees.
- Everyday clothing.
- Personal gifts.
- Fines and penalties.
- Income tax itself.
- Home costs if you have not declared business use in the census.
VAT and income tax: two taxes, two sets of rules
An expense being deductible for one does not make it deductible for the other.
| Income tax | VAT (form 303) | |
|---|---|---|
| What you deduct | The net amount of the expense | The input VAT |
| Document | Invoice (preferable) or valid receipt | Full invoice with your details and VAT shown separately |
| Simplified invoice | Accepted as evidence | Only if it shows your tax ID, address and the VAT separately |
| If your activity is VAT-exempt | Input VAT becomes part of the cost | You cannot deduct it |
| If you forgot it | Amend your income tax return | Include it in a later form 303 within 4 years |
- Price before VAT
- €1,200
- 21% VAT, deductible on that quarter's form 303
- €252
- Income tax depreciation: €1,200 × 26%
- €312/year
€312 for each full year until the €1,200 is written off. In the first year, in proportion to the months of use.
How to prepare for a tax review
Quarterly order and evidence of business use.
The Tax Agency can review your expenses for four years after the filing deadline. The best defence is to keep everything in order from the start.
- Invoices in digital form, organised by quarter.
- Each expense entered in your records with its business-use percentage.
- Evidence of business use: contracts, client emails, visit logs, photos of your study.
- A quarterly check against the previous quarter.
The deductible expenses calculator helps you estimate the saving, and your adviser can confirm borderline cases.
Frequently asked questions
Can I deduct expenses with a till receipt instead of an invoice?
A receipt without your details does not let you deduct VAT and is weak evidence for income tax. Always ask for an invoice in your name with your tax ID; in most shops you just need to request it when paying.
Are self-employed contributions deductible?
Yes. RETA contributions, including the flat rate, are fully deductible for income tax. They carry no VAT, so they do not appear on form 303.
How much of my electricity can I deduct if I work from home?
30% of the business share of your home. If your study takes up 20% of the property, you deduct 6% of the bill, provided you have declared that business use on form 036.
Can I deduct my car if I also use it for holidays?
Not for income tax, unless your activity is one of the exceptions in the regulations, such as a sales agent. For VAT you can generally deduct 50% of the input tax.
What if I forget to deduct an expense?
For VAT you can include it in a later form 303 within the following four years. For income tax, if you have already filed your return, you can amend it so the Tax Agency refunds any overpayment.
Official sources
- Law 35/2006 on Personal Income Tax (Art. 30: special expense rules)
- Income Tax Regulations (Arts. 9, 22 and 30)
- Law 37/1992 on VAT (Art. 95: capital goods and vehicles)
- Law 27/2014 on Corporate Income Tax (Arts. 15 and 103)
- Law 7/2012 (Art. 7: cash payment limit)
- Invoicing Regulations (Royal Decree 1619/2012)
- Spanish Tax Agency: utilities for a home used for business
- Spanish Tax Agency: simplified depreciation table
- Spanish Tax Agency: expenses of the business owner
Would you rather we handled it?
Our advisors take care of your paperwork and answer within 24 hours.
Request a free consultation