Sole trader or limited company in Spain? When each pays in 2026
Moving from sole trader to limited company (SL) is often decided with a rule of thumb like «above so many euros an SL pays off». The real answer depends mainly on how much money you need to take out of the business each year. Here we compare both options with the figures in force in 2026 and an example at five profit levels.
Two ways of taxing the same profit
Progressive income tax for the sole trader; Corporate Income Tax and, on distribution, dividend tax for the SL.
A sole trader adds business profit to the general income tax base, which has a progressive state scale and a regional one. In the Community of Madrid the combined marginal rate looks like this:
| Taxable base | Marginal rate (State + Madrid) |
|---|---|
| Up to €12,450 | 18% |
| €20,200 to €35,200 | 27.8% |
| €35,425.68 to €57,320.40 | 35.9% |
| €60,000 to €300,000 | 43% |
| Over €300,000 | 45% |
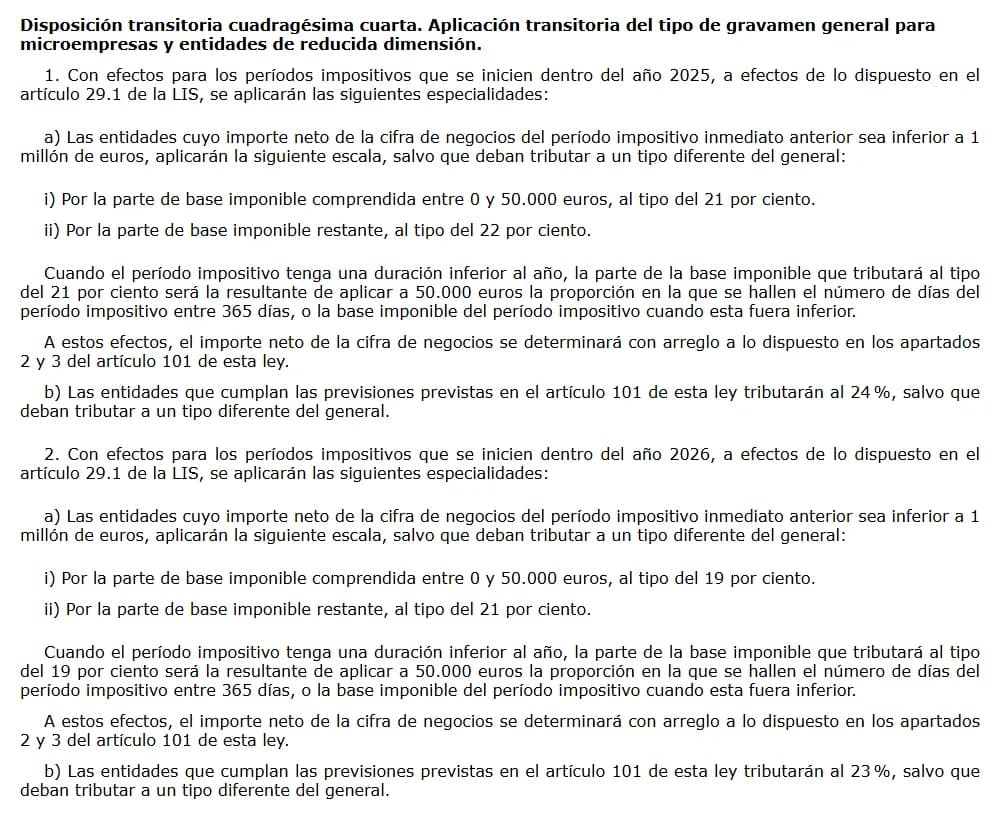
The company pays Corporate Income Tax. The standard rate is 25%, but Law 7/2024 is gradually lowering the rate for small companies.
| Type of company in 2026 | Rate |
|---|---|
| Micro-company (prior-year turnover below €1 million) | 19% up to €50,000 of taxable base and 21% on the rest |
| Small company (turnover below €10 million) | 23% |
| Newly created company | 15% in the first year with a positive base and the next |
| Others | 25% |
The company's profit is not the shareholder's money. If it is paid out as a dividend, it is taxed again in their income tax, in the savings base.
| Dividends (savings base) | Rate |
|---|---|
| Up to €6,000 | 19% |
| €6,000 to €50,000 | 21% |
| €50,000 to €200,000 | 23% |
| €200,000 to €300,000 | 27% |
| Over €300,000 | 30% |
- 19% Corporate Income Tax + 19% on the dividend
- 34.4%
- 21% Corporate Income Tax + 21% on the dividend
- 37.6%
If everything is paid out, the burden is very close to the sole trader's marginal income tax. The SL's advantage lies in what stays inside.
Social security: sole trader versus company director
The director has a higher minimum base, and dividends count too.
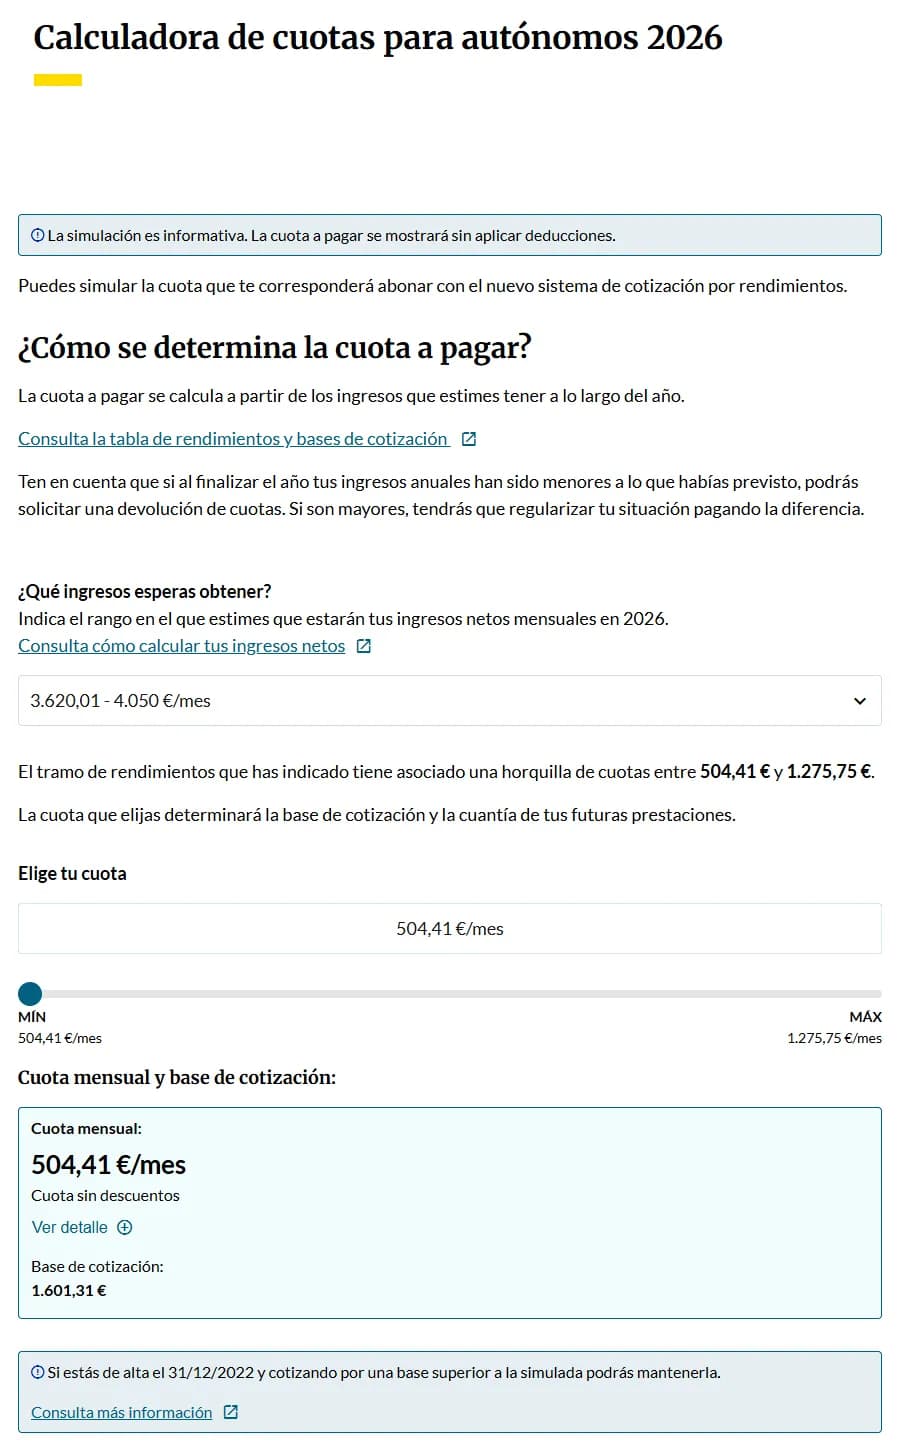
In 2026 contributions still follow the 15 net-earnings bands of 2025, with a total rate of 31.50%. To find your band, 7% is deducted from net earnings for general expenses, or 3% if you are a partner in a trading company.
| Annual profit before contributions | Band | Minimum contribution for a sole trader |
|---|---|---|
| €30,000 | 9 | €401.47 a month |
| €50,000 | 13 | €504.41 a month |
| €70,000 | 14 | €545.59 a month |
| €80,000 or more | 15 | €607.35 a month |
- €1,424.40
- minimum base for company directors in 2026
- €448.69
- resulting minimum monthly contribution
- 33%
- of the capital (25% if you are a director): from there your dividends count for your band
A shareholder who controls and runs the company registers as a self-employed company director. Their band takes into account both the pay they receive and their dividends if they own at least 33% of the capital, or 25% as a director. Since contributions are adjusted with Tax Agency data, paying dividends also pushes contributions up.
Liability: what a company really protects
An SL limits liability to the capital, but it has well-known gaps.
A sole trader is liable for business debts with all their present and future assets. The limited-liability entrepreneur scheme protects a main home worth up to €300,000 from certain business debts, but not from the Tax Agency or Social Security.
In a limited company, shareholders are only liable up to the capital contributed. These are the most common exceptions:
- Personal guarantees signed by the shareholder, for example with the bank.
- A director who fails to start winding-up when losses take net assets below half the share capital is liable for later debts.
- Tax and Social Security debts can be passed on to the director if the business stops trading irregularly.
- With capital below €3,000, if the company is wound up without enough assets, shareholders are liable for the shortfall up to that figure.
Set-up and running costs
Setting one up is cheap; running it, less so.
- €1
- minimum capital since Law 18/2022
- €60 + €40
- notary and registry fees with standard articles and capital up to €3,100
- €0
- tax: incorporation is exempt from capital duty
With bespoke articles and professional advice, incorporation usually costs between €300 and €1,000, including the name certificate from the Central Companies Registry.
What really counts is the company's day-to-day running:
- Accounts under the Spanish General Accounting Plan.
- Legalisation of books and filing of annual accounts with the Companies Registry.
- Corporate Income Tax and its instalments.
- Withholding on the director's pay.
- Mandatory electronic notifications.
How the shareholder gets paid: salary or dividends
Each route has its own requirements and tax treatment.
| Director's pay | Dividends | |
|---|---|---|
| Requirement | Articles stating the post is paid and a general meeting setting the annual maximum | Profits approved by the general meeting and legal reserve funded |
| Deductible for the company? | Yes, if the requirements are met | No |
| Withholding | 35% (19% if the company's turnover is under €100,000) for directors' fees | 19% |
| In your income tax | General base, at your marginal rate | Savings base, 19% to 30% |
If the company provides professional services and you perform them while registered as self-employed, that pay is treated as business income for income tax. In every case it is a related-party transaction and must be at market value.
Taking money out without documenting it as salary, dividend or loan causes serious problems in a tax inspection.
Worked example at five profit levels
Total burden and money available under each option, with 2026 figures.
- Madrid resident, no children, under 65 and no other income.
- Sole trader: simplified direct assessment, 5% hard-to-document expenses (max. €2,000) and the minimum contribution for their band.
- SL: micro-company that is not newly created, director's salary of €35,000 taxed as employment income, director's contribution deducted in their income tax and €1,500 of extra costs.
- The burden includes income tax, contributions, Corporate Income Tax, dividend tax and those costs.
| Profit | Sole trader: burden (net) | SL retaining: burden | SL retaining: your net + retained | SL paying out all: burden (net) |
|---|---|---|---|---|
| €30,000 | €8,824 (€21,176) | €10,111 | €19,889 + €0 | €10,111 (€19,889) |
| €50,000 | €15,606 (€34,394) | €14,519 | €24,546 + €10,935 | €17,142 (€32,858) |
| €70,000 | €23,289 (€46,711) | €18,319 | €24,546 + €27,135 | €24,700 (€45,300) |
| €100,000 | €36,612 (€63,388) | €24,289 | €24,546 + €51,165 | €36,275 (€63,725) |
| €150,000 | €58,112 (€91,888) | €34,789 | €24,546 + €90,665 | €55,860 (€94,140) |
- Profit before salary and costs
- €100,000
- Extra SL costs
- − €1,500
- Director's salary
- − €35,000
- Company taxable base
- €63,500
- CIT: €50,000 × 19% + €13,500 × 21%
- − €12,335
- Retained in the company
- €51,165
From the salary, after the director's contribution (€5,435) and income tax (€5,019), you keep €24,546.
Where the tipping point lies
It depends on whether you need the money or can leave it in the business.
| Profit | SL saving when retaining | SL saving when paying out everything |
|---|---|---|
| €50,000 | €1,087 | − €1,536 (worse) |
| €70,000 | €4,970 | − €1,411 (worse) |
| €100,000 | €12,323 | €337 |
| €150,000 | €23,323 | €2,252 |
If you need to take out all the profit, an SL barely pays off until around €100,000, and even at €150,000 the gain is about €2,250 a year. If you can leave a meaningful part inside, the company reduces the burden from around €45,000-50,000 of profit.
- The risk of the activity and whether you will sign personal guarantees.
- Whether there will be several partners, investors or a need for finance, where an SL is almost essential.
- Transferring the business: clients, contracts, assets and VAT should be planned to avoid unnecessary costs.
- That the 15% new-company rate does not apply if you transfer your own activity.
Frequently asked questions
Can I choose a low contribution as a company director?
Not below the minimum base, which in 2026 is €1,424.40 (€448.69 a month). During 2026 you may provisionally keep your 2025 base, but the annual adjustment will apply the minimum. If your earnings, including dividends, put you in a higher band, that will be adjusted too.
Is it better to take a salary or dividends?
Salary reduces Corporate Income Tax but is taxed at your marginal rate; dividends are taxed twice. In Madrid it is usually sensible to take a salary until your marginal income tax rate approaches the combined company-plus-dividend cost of 34-38%, and leave the rest in the company.
If I move my sole-trader business into an SL, will I pay 15%?
Usually not. The law does not treat as a new activity one carried out the year before by an individual holding more than 50% of the company. You would pay the micro-company rate: 19% and 21% in 2026.
What do I do with the money left in the company?
It must be used for the business: investment, cash reserves or growth. It cannot be used for personal spending without documenting it. If more than half of the assets stop being used in the business, the company may be treated as an asset-holding company and lose the reduced rates.
When is a good time to switch from sole trader to SL?
When profit is stable and higher than what you need to live on, ideally at the start of a financial year to keep accounts and returns simple. Run a simulation with your real figures first.
Official sources
- Law 27/2014 on Corporate Income Tax (Art. 29 and 44th transitional provision)
- Spanish Tax Agency: Corporate Income Tax rates
- Law 35/2006 on Personal Income Tax (general and savings scales; directors' withholding)
- Community of Madrid Legislative Decree 1/2010 (regional income tax scale)
- Order PJC/297/2026 on contributions for 2026
- Social Security: contribution bases and rates 2026
- Social Security: new contribution system for the self-employed
- Capital Companies Law (Arts. 4, 274, 363 and 367)
- Law 14/2013 supporting entrepreneurs (limited-liability entrepreneur)
- Royal Decree 421/2015 (standard articles and fees)
- Royal Decree-law 13/2010 (Art. 5: incorporation fees)
- Transfer Tax and Stamp Duty consolidated law (Art. 45: incorporation exemption)
Would you rather we handled it?
Our advisors take care of your paperwork and answer within 24 hours.
Request a free consultation